- How This List Was Put Together
- The Backdrop for SIP Investors in October 2026
- What Five-Year SIP Data Actually Shows
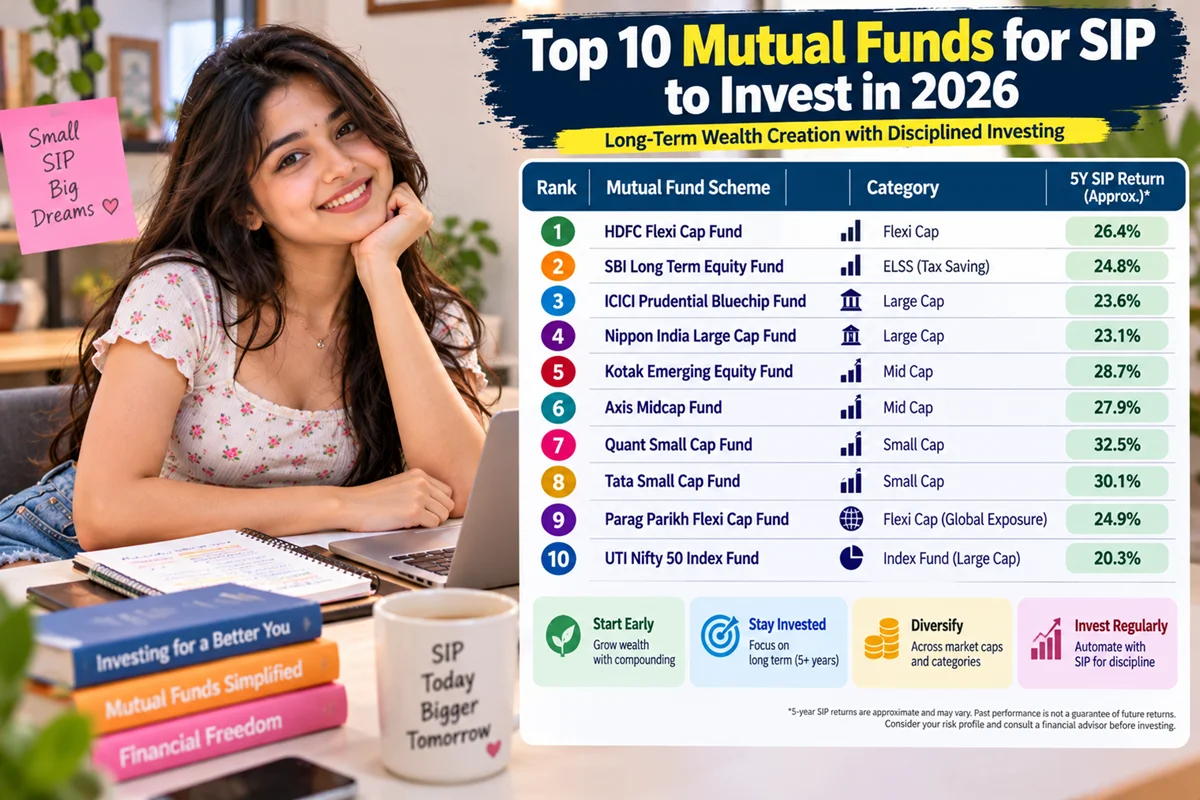
- The 10 Funds, Grouped by Job
- Core Holdings: Flexi Cap, Large Cap and Index
- 1. Parag Parikh Flexi Cap Fund
- 2. HDFC Flexi Cap Fund
- 3. ICICI Prudential Large Cap Fund
- 4. Canara Robeco Bluechip Equity Fund
- 5. A Nifty 50 Index Fund
- Cushion: Hybrid
- 6. ICICI Prudential Equity & Debt Fund
- Growth: Mid Cap
- 7. HDFC Mid-Cap Opportunities Fund
- 8. Motilal Oswal Midcap Fund
- Satellite: Small Cap
- 9. Invesco India Smallcap Fund
- 10. Bandhan Small Cap Fund
- At a Glance
- Why You Shouldn’t Buy All Ten
- What a SIP Could Grow To
- Direct Plan or Regular Plan?
- A Quick Checklist Before You Start
- How SIP Gains Are Taxed
- Mistakes That Quietly Cost SIP Investors
- Where to Verify the Latest Numbers
- Conclusion
Search for the best SIP fund and you’ll find a hundred lists, each crowning a different winner. That isn’t carelessness. “Best” shifts with the date you check, the return period you pick, and whether you care more about growth or about sleeping through a 15% market drop.
So here’s the honest framing. This is a shortlist, not a prediction. The ten funds below kept turning up on published 2026 lists from Indian investing platforms, and together they cover the main categories a SIP investor actually chooses between: flexi cap, large cap, index, hybrid, mid cap and small cap.
The goal is to help you work out which two or three suit your situation. It is not to suggest you buy all ten. Please don’t.
How This List Was Put Together
I went through 2026 shortlists from several platforms and research blogs, including Kuvera, Fibe, Univest and Scripbox. A fund made the cut if it appeared on more than one list, and I then balanced the picks by category so the list isn’t ten versions of the same bet.
Two funds are exceptions, and I’ll flag them when we reach them. They appeared on fewer lists and are here mainly to cover a category.
What I did not do: run my own return ranking, or check each fund’s current portfolio, expense ratio or manager. Those details change, and any article that hard-codes them goes stale within weeks. Before you invest, read the latest factsheet on the fund house’s website. Scheme names also change when SEBI recategorises funds, so confirm the exact current name there too.
The Backdrop for SIP Investors in October 2026
Monthly SIP contributions have been running above ₹30,000 crore in 2026, according to AMFI-based reporting, so you’re hardly alone in doing this. The habit has gone properly mainstream.
The rate environment just changed, though. On October 7, the RBI raised the repo rate by 25 basis points to 5.50%, its first hike since February 2023, and moved its stance to “calibrated tightening”. Higher rates tend to make fixed deposits look more attractive and can make markets jumpy for a while.
None of that changes the basic logic of a SIP, which is to invest a fixed amount on a schedule so you aren’t betting on one entry date. It does mean you should expect some bumpy months and decide in advance that you won’t stop the SIP because of them.
What Five-Year SIP Data Actually Shows
A Kuvera analysis of five-year SIP returns published this year found a few patterns worth knowing:
- Small and mid cap funds dominated the leaderboard. Nine of the top ten funds belonged to those two categories, with annualised SIP returns above 20%.
- No actively managed large cap fund made the top ten. The best active large cap fund managed an annualised five-year SIP return of 14.27%.
- Bandhan Small Cap Fund ranked first among 26 small cap funds in that comparison.
Before you rush toward small caps, read the next point twice. High returns and high risk travel together. Those categories also fall harder in weak markets, and a five-year window that happens to include a strong run flatters them.
Why you’ll see different numbers for the same fund. Across the lists I read, five-year figures for a single well-known flexi cap fund ranged from the low teens to above 20%. They weren’t lying. Some measured point-to-point CAGR, others measured SIP returns using XIRR (the method that accounts for money going in on different dates), and they were calculated on different days. Always check which measure a number uses and when it was calculated.
The 10 Funds, Grouped by Job
The “relative risk” label below is my own ranking of these funds against each other. It is not the official SEBI riskometer, which you’ll find on each fund’s page.
Core Holdings: Flexi Cap, Large Cap and Index
1. Parag Parikh Flexi Cap Fund
Flexi cap | Relative risk: medium-high | Sensible horizon: 7+ years
This was the most frequent name across the lists I read. Flexi cap means the manager can move between large, mid and small companies as they see fit. This fund has also held a slice of overseas stocks, which gives it a different return pattern from purely Indian peers.
Worth checking: its current overseas allocation, and whether the fund house is accepting new SIPs without restrictions.
2. HDFC Flexi Cap Fund
Flexi cap | Relative risk: medium-high | Sensible horizon: 7+ years
The other flexi cap name you’ll see beside Parag Parikh on most shortlists. Because both sit in the same category, holding both gives you less diversification than it feels like. Many investors simply pick one.
Worth checking: the sector split and top holdings on the latest factsheet, so you know what you’re really buying.
3. ICICI Prudential Large Cap Fund
Large cap | Relative risk: medium | Sensible horizon: 5+ years
Under SEBI’s categories, large caps are the 100 biggest listed companies by market value. A fund like this tends to fall less than mid and small cap funds in a sell-off, and it also tends to rise less in a rally. Many older lists still call it the Bluechip Fund.
Worth checking: how it has done against a plain Nifty 50 index fund over several years, since that’s the honest benchmark for any active large cap fund.
4. Canara Robeco Bluechip Equity Fund
Large cap | Relative risk: medium | Sensible horizon: 5+ years
Another large cap name that appeared across the lists, and a reasonable alternative if you’d rather not hold the ICICI fund. You’d normally pick one of these two large cap funds, not both.
Worth checking: the exact scheme name on Canara Robeco’s website, because some lists label it differently.
5. A Nifty 50 Index Fund
Index | Relative risk: medium | Sensible horizon: 5+ years
I’m deliberately not crowning one scheme here. Index funds that track the Nifty 50 are close to identical, and the differences come down to the expense ratio and tracking error (how closely the fund follows the index). Widely held examples include UTI Nifty 50 Index Fund and HDFC Index Fund Nifty 50 Plan, but several fund houses offer near-twins.
The reason this slot exists is that active large cap funds struggled in the Kuvera data. For a beginner’s first SIP, a low-cost index fund is hard to beat on simplicity. Direct-plan expense ratios are often well below 0.5%, but confirm the current figure.
Cushion: Hybrid
6. ICICI Prudential Equity & Debt Fund
Aggressive hybrid | Relative risk: medium-lower | Sensible horizon: 5+ years
This one appeared on fewer lists than the others, and it’s here to represent the hybrid category. Funds like this hold a mix of equity and debt, with equity of at least 65%. That usually smooths the ride compared with a pure equity fund, though it is not a safe fund, and it’s still taxed like an equity fund.
Worth checking: the current equity-to-debt split, which can move.
Growth: Mid Cap
7. HDFC Mid-Cap Opportunities Fund
Mid cap | Relative risk: high | Sensible horizon: 7+ years
Mid caps are the companies ranked roughly 101 to 250 by market value. They’ve historically offered more growth than large caps, with deeper falls along the way. This fund showed up on several lists and is one of the more frequently named in the category.
Worth checking: its fall during past market corrections, not only its returns. If a 25–30% dip would make you stop your SIP, size this fund smaller.
8. Motilal Oswal Midcap Fund
Mid cap | Relative risk: high | Sensible horizon: 7+ years
A second mid cap name from the lists. It has historically been run with a more concentrated portfolio than many peers, which can amplify both good and bad stretches.
Worth checking: the number of holdings and how much of the fund sits in its top ten stocks.
Satellite: Small Cap
9. Invesco India Smallcap Fund
Small cap | Relative risk: highest on this list | Sensible horizon: 10+ years
It appeared on several of the lists, including Kuvera’s five-year small cap ranking. Small caps can deliver the biggest gains and the sharpest drops in the same year, which is why most people treat them as a small slice of the SIP, not the whole thing.
Worth checking: whether the fund is accepting SIPs freely. Fund houses sometimes limit inflows into small cap schemes when the category gets crowded.
10. Bandhan Small Cap Fund
Small cap | Relative risk: highest on this list | Sensible horizon: 10+ years
It ranked first among 26 small cap funds on five-year SIP returns in the Kuvera analysis. It’s a relatively young fund with a shorter track record than most here, so that strong five-year number mostly captures one stretch of the market.
Worth checking: how it behaved in the weaker months of that period, not only the headline figure.
Also frequently listed, if you want alternatives. Nippon India Small Cap Fund, Nippon India Growth Mid Cap Fund, Edelweiss Mid Cap Fund, Motilal Oswal Large and Midcap Fund, HDFC Large & Mid Cap Fund and Mirae Asset Emerging Bluechip Fund all appeared on at least one of the published lists I reviewed.
At a Glance
| # | Fund | Category | Relative risk | Horizon | Role |
|---|---|---|---|---|---|
| 1 | Parag Parikh Flexi Cap | Flexi cap | Medium-high | 7+ yrs | Core |
| 2 | HDFC Flexi Cap | Flexi cap | Medium-high | 7+ yrs | Core |
| 3 | ICICI Pru Large Cap | Large cap | Medium | 5+ yrs | Core |
| 4 | Canara Robeco Bluechip Equity | Large cap | Medium | 5+ yrs | Core |
| 5 | Nifty 50 index fund | Index | Medium | 5+ yrs | Core, low cost |
| 6 | ICICI Pru Equity & Debt | Aggressive hybrid | Medium-lower | 5+ yrs | Cushion |
| 7 | HDFC Mid-Cap Opportunities | Mid cap | High | 7+ yrs | Growth |
| 8 | Motilal Oswal Midcap | Mid cap | High | 7+ yrs | Growth |
| 9 | Invesco India Smallcap | Small cap | Highest | 10+ yrs | Satellite |
| 10 | Bandhan Small Cap | Small cap | Highest | 10+ yrs | Satellite |
Why You Shouldn’t Buy All Ten
Ten funds from one article is a recipe for overlap. Two flexi cap funds and two large cap funds will hold many of the same big stocks, so you pay several expense ratios for roughly one bet. Most people are well served by two to four funds.
Here are three illustrative ways people commonly split a ₹10,000 monthly SIP. They’re examples of structure, not recommendations, and your own split should come from your goal and how you’d react to a bad year.
| Style | Example split of ₹10,000 |
|---|---|
| Steadier | ₹5,000 Nifty 50 index + ₹3,000 flexi cap + ₹2,000 hybrid |
| Balanced | ₹4,000 index or large cap + ₹3,000 flexi cap + ₹2,000 mid cap + ₹1,000 small cap |
| Growth-leaning | ₹3,000 flexi cap + ₹2,000 index + ₹3,000 mid cap + ₹2,000 small cap |
Notice that even the growth-leaning split keeps a core of flexi cap and index. Mid and small cap work best as a satellite around that core.
What a SIP Could Grow To
The table below shows what ₹10,000 a month could become at different assumed annual returns. These are arithmetic illustrations, not forecasts. Real equity returns arrive unevenly, and some years will be negative.
| Assumed annual return | 10 years (you invest ₹12 lakh) | 15 years (you invest ₹18 lakh) |
|---|---|---|
| 8% | ₹18.4 lakh | ₹34.8 lakh |
| 10% | ₹20.7 lakh | ₹41.8 lakh |
| 12% | ₹23.2 lakh | ₹50.5 lakh |
| 14% | ₹26.2 lakh | ₹61.3 lakh |
Calculated with the return split evenly across 12 months and money invested at the start of each month, before tax and costs. The takeaway is the gap between 10 and 15 years. Extra time does more for you than a couple of extra percentage points of return.
Direct Plan or Regular Plan?
Every fund above comes in two versions. A direct plan has a lower expense ratio because no distributor commission is built in, and you invest through the fund house’s own website or app, or a direct-plan platform. A regular plan costs a little more each year, and part of that cost pays the intermediary who helps you.
If you’re comfortable choosing funds yourself, direct is usually the cheaper route. If you want a human to guide you and rebalance for you, regular can be worth the cost. A small yearly difference in cost compounds noticeably over fifteen years, so make that choice deliberately.
A Quick Checklist Before You Start
- Finish your KYC. It’s mandatory for any mutual fund investment and can be done online.
- Write down the goal and the date. A goal five years out and a goal fifteen years out need different funds.
- Open the latest factsheet. Check the expense ratio, top holdings, fund manager and fund size.
- Check the riskometer and exit load. Exit load is a fee for selling within a set period.
- Pick a SIP date just after your income arrives. That way the auto-debit never strains your month.
- Switch on the step-up option if your platform offers it, so your SIP rises as your income does.
How SIP Gains Are Taxed
For equity-oriented funds (those holding at least 65% in Indian equities), the rules for FY 2026-27 are unchanged from the post-July 2024 framework, and Budget 2026 did not alter them:
- Sold within 12 months: short-term gains taxed at 20%.
- Sold after 12 months: long-term gains taxed at 12.5%, but only on total long-term gains above ₹1.25 lakh in a financial year.
Two details trip people up. Each monthly SIP instalment has its own 12-month clock, and when you sell, units are generally treated as sold first-in, first-out. Also, the ₹1.25 lakh exemption is shared across all your equity gains in the year, including direct stocks.
A quick example: Suppose you book ₹3 lakh of long-term gains in a year. The first ₹1.25 lakh is exempt, leaving ₹1.75 lakh taxable at 12.5%, which is ₹21,875. Add 4% cess (₹875) and the tax comes to ₹22,750.
If you’re eyeing an ELSS (tax-saving) fund, remember the 3-year lock-in applies to each instalment. The Section 80C deduction is available only under the old tax regime. Debt fund gains are taxed at your slab rate.
Mistakes That Quietly Cost SIP Investors
- Stopping during a downturn. That’s when your SIP buys the most units for the same money.
- Chasing last year’s top performer. Leaderboards reshuffle, and the fund that topped one year often lags the next.
- Holding too many funds. More names rarely means more diversification.
- Overloading on small and mid caps. They suit a slice of the SIP, not all of it.
- Ignoring costs. A higher expense ratio is a guaranteed drag, while higher returns are only a hope.
- Forgetting to raise the SIP. An amount that felt big in year one is small by year seven.
- Checking the NAV daily. It invites reactions that work against the whole idea of a SIP.
Where to Verify the Latest Numbers
- AMFI for industry data and scheme information.
- The fund house’s own website for the current factsheet, portfolio, expense ratio and scheme name.
- Kuvera’s 2026 SIP analysis for the five-year category findings quoted above.
- Tata Mutual Fund’s post-Budget 2026 tax note for equity fund taxation.
Conclusion
The most useful way to read any top-10 list is as a menu of categories, with a few well-regarded examples in each. Start with your goal and your horizon. Choose the category that fits, then one or two funds within it. Set the SIP date, switch on the annual step-up, and leave it alone.
The funds above are a reasonable place to begin your research in October 2026. They aren’t a promise. Past returns won’t repeat on schedule, and the fund that suits your neighbour may be wrong for you. If you remember only one thing, remember that staying invested through the dull and frightening months matters far more than picking the perfect fund.
Disclaimer: This article is general information for educational purposes and is not personalised investment advice. The funds named reflect commonly published shortlists and are not recommendations to buy. Mutual fund investments are subject to market risks; read all scheme-related documents carefully. Past performance does not guarantee future results. Fund details, tax rules and returns change, so verify the latest information with the fund house and a SEBI-registered investment adviser before investin